Independent Australian and global macro analysis

Thursday, December 17, 2020

Australian MYEFO 2020/21: Improved outlook as economy rebounds

The Mid-Year Economic and Fiscal Outlook (MYEFO) update to the Australian Federal Budget for 2020/21 was presented by the Treasurer today. The key dynamics are that momentum in the domestic economy since the reopening from its covid-19 shutdown has been stronger than initially expected, helped by the containment of the virus and eased restrictions, while key commodity prices have run well ahead of estimates. These factors have combined to improve the budget position by $23.9bn over the forward estimates, with the deficit for the current financial year expected to come in at 9.9% of GDP, revised down from 11% previously.   

MYEFO 2020/21 | Budget Position

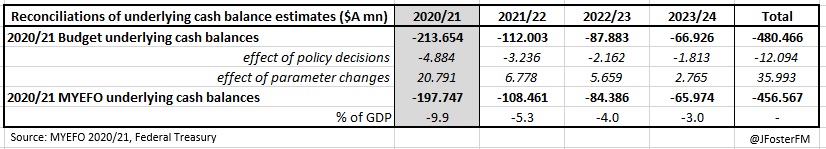
The forecast for the budget deficit in 2020/21 has narrowed to $197.7bn (-9.9% of GDP) from $213.7bn (-11.0% of GDP) estimated when the Federal Budget was handed down in early October, with an improved economic outlook driving the revision. Thereafter, the profile of the deficit has lowered to $108.5bn in 2021/22 ($112.0bn previously) and $84.4bn in 2022/23 ($87.9bn), with the projection for the deficit in 2023/24 little changed at around $66bn from $66.9bn. In total, the outlook for the budget position has improved by $23.9bn over the 4 year period of the forward estimates out to 2023/24. 


For 2020/21, the $15.9bn upgrade to the forecast deficit to $197.7bn reflects the impact of improved economic conditions, with the effect of parameter changes giving a $21bn boost to the budget through factors including a lower take-up of the JobKeeper policy and higher tax receipts. New policy announcements since the October budget are modest at $4.9bn. This centres on a 3-month extension to the Coronavirus Supplement from January 1 to March 31 2021 at a cost of $3.2bn. Income support recipients (including JobSeeker) will receive a $150 payment per fortnight over the period under the announcement. Meanwhile, an additional $1.5bn has been allocated to accessing covid-19 vaccines ($0.7bn in 2020/21 and $0.9bn in 2021/22). 

Across the entire forward estimates period, an upgraded economic outlook adds around $36bn to the budget, driven by a higher tax-take with receipts rising by $22bn, while new policy measures cost $12.1bn - the net result equating to the $23.9bn improvement to the budget position. The profile for government net debt has been revised to a lower trajectory at 34.5% of GDP in 2020/21 (from 36.1%) to 43% in 2023/24 (from 43.8%).


MYEFO 2020/21 | Economic Forecasts

A stronger and earlier rebound in economic activity since the national reopening underpins Treasury's revised set of forecasts. The key is the improvement to near-term momentum following the 3.3% rebound in GDP reported in the September quarter. Real GDP growth for 2020/21 has been upgraded to 0.75% from a 1.5% contraction assumed in the Federal Budget. With more activity coming through earlier than previously expected, the projection for 2021/22 was lowered to 3.5% from 4.75%, while the forecasts for 2022/23 (2.5%) and 2023/24 (2.75%) were both lowered by 0.25ppt. On this outlook, real GDP is forecast to be restored to its pre-pandemic level by Q2 2021.  


The stronger GDP growth profile has resulted in a more constructive view on employment growth near term, revised up to 4.0% from 2.75% in 2020/21. But the unemployment rate is still forecast to hold at 7.25% in the current financial year, before moving to a lower profile than assumed in the Federal Budget, falling to 5.25% by the end of 2023/24. Meanwhile, the outlook for wages growth remains subdued and was revised lower to 1.25% in 2021/22. 

Despite the recent surge in global commodities prices, partly attributable to an improvement in global growth (see below), Treasury anticipates these elevated levels will retrace such that it elected to retain its forecast for iron ore at US$55/t, albeit with the timing pushed back by 3 months to Q3 2021. The effect of the surge in iron ore prices was reflected in the upgrade in the forecast for nominal GDP growth to 1.0% from -1.75% in 2020/21, though with prices then unwinding the outlook for 2021/22 was downgraded to 1.25% from 3.25% previously.


MYEFO 2020/21 | Summary

The recovery in the Australian economy is well underway with activity rebounding at a faster pace than previously expected. Reflecting these developments, the budget has been updated to reflect this improving outlook. New initiatives in today's update added modestly to the Australian Government's fiscal response to the pandemic crisis, with total policy support standing at $164.7bn in the current financial year.

Wednesday, December 16, 2020

Australian employment +90.0k in November; unemployment rate 6.8%

The momentum in Australia's labour market recovery gathered pace in November with employment again outperforming expectations in rising by 90.0k in the month on a wider reopening effort taking place across the nation. The headline unemployment rate declined to 6.8% from 7.0% as the participation rate jumped above its pre-pandemic level, and hours worked advanced by 2.5% in the month.  

Labour Force Survey — November | By the numbers
  • Employment (on net) increased by 90.0k in November to come in well above the censuses estimate of 40.0k. A minor upward revision saw employment in October adjusted higher by the ABS to 180.4k from 178.8k.   
  • Australia's unemployment rate declined by 0.2ppt to 6.8%, whereas markets had anticipated it to hold steady at 7.0%. 
  • A further uplift of 0.3ppt drove the participation rate to 66.1% to a level that now exceeds where it was when the pandemic emerged.
  • Total hours worked increased in the month at an accelerated pace of 2.5% to 1.752bn hours, reducing the decline over the year to -1.2% from -3.5%. 


Labour Force Survey — November | The details

In a very encouraging report today, employment increased by a much stronger-than-expected 90.0k in November to add more velocity to a recovery that regained momentum with a 180.4k rise in October. Victoria was again the key contributor with a further 74.0k jobs added back to its economy following on from the 81.7k increase in the previous month as the state positioned for reopening from its shutdown. Employment also lifted in New South Wales (23.8k), Western Australia (11.4k) and Tasmania (2.0k), though it declined in Queensland (-20.4k) and South Australia (-0.9k).   


This 90.0k gain in national employment was sufficient to drive the unemployment rate lower to 6.8% from 7.0% — even as the participation rate advanced to 66.1% from 65.8%. Remarkably, participation is now higher than it was before the pandemic emerged (was 65.9% in March); a development that speaks to the level of dynamism evident in this economy as it reopens more widely. On top of all of this was a 2.5% rise in hours worked, which is its fastest month-on-month acceleration since June soon after the time when the national shutdown had started to be eased. 


In terms of the state of the recovery, employment is now around 1.1% lower than its pre-pandemic level, with around 84% of this year's earlier job losses now restored, while hours worked have improved to be 1.5% lower than their pre-pandemic level from a trough of -10.4%. The key point to note is that hours worked have nearly caught up with employment in this recovery phase in a sign of improving activity across the economy through a broader reopening. 


In our preview of today's report, we highlighted that the focus would be on the compositional detail for the employment number. This followed that in October, significant strength in the full-time segment emerged for the first time in the recovery, which, to that point, had been driven by part-time work. The interest was in seeing whether that would continue as a sign of a broadening improvement in underlying economic conditions given that employment and hours worked in the part-time segment were already back to around their pre-pandemic levels. Pleasingly, this is what occurred with full-time employment increasing by 84.2k in the month adding to October's 98.7k gain (revised up from 97.0k). As the chart, below shows, the full-time segment is still lagging well behind part-time on both employment and hours worked, but it has now established considerable momentum as the economic fundamentals have strengthened.  


As a result of the surge in full-time work and more hours worked being completed, levels of underutilisation in the labour market have come down. While the unemployment rate fell from 7.0% to 6.8%, much larger declines were recorded in the underemployment rate -1.0ppt to 9.4% and in the underutilisation rate -1.2ppts to 16.2%.


Labour Force Survey — November | Insights

All key measures in the labour market improved in November in an encouraging sign of the momentum and progress in the recovery. The increased strength in full-time employment and rise in participation are both particularly encouraging. Overall, with the economy now opening up more widely with fewer disruptions and restrictions, activity is rebounding and employment and hours worked reflect this. The key in 2021 is to sustain the momentum, with the labour still currently a long way from where it needs to be.

Preview: Labour Force Survey, November

At 11:30am (AEDT) today, the ABS is due to publish its Labour Force Survey for the month of November. Going into the report, the background is constructive after Australia's labour market recovery regained significant momentum in October as employment surged up by 178.8k, with a strong outcome coming through in Victoria (81.6k) as the state positioned for reopening. However, this was not enough to prevent the unemployment rate from backing up slightly to 7.0%, which reiterated that there is still a long road to recovery ahead.

As it stands | Labour Force Survey

In October, employment (on net) rebounded very strongly with a 178.8k increase to defy market expectations for a 27.5k fall. This came after a weak report in the month prior where employment contracted by 42.5k that mainly reflected the impact of Victoria's shutdown. But this then gave way to preparations for the reopening as employment in the state increased by 81.6k to drive the headline rise at the national level. Employment in all other mainland states also posted increases in the month.


A notable aspect of October's gain was that it was driven by full-time employment, which lifted by 97.0k compared to an 81.8k increase from the part-time segment. This was the first month since the recovery commenced in June where the outcome for full-time employment has outperformed the part-time category. The key question is whether this is an early sign of the recovery broadening out as employment and hours worked in the part-time segment have largely been restored to their pre-pandemic levels, albeit with considerable compositional shifts occurring across industries.


With the participation rate rising sharply to 65.8% from 64.9% — driven mainly by a 2.0ppt increase in Victoria (65.0%) ahead of the reopening — the national unemployment rate lifted from 6.9% to 7.0%, though markets had expected a large increase to 7.2%. Spare capacity more broadly declined but was still elevated — underemployment falling 1.0ppt to 10.4% and underutilisation down 0.9ppt to 17.4% — as hours worked in the month of October advanced by 1.2% (-3.4%Y/Y). For a full review of October's report see here.


Market Expectations | Labour Force Survey

The consensus estimate for today's report is for employment to rise by a further 40k in November. As has been the case during this pandemic period, the range of estimates is again very wide between -10k and +100k. The national unemployment rate is anticipated to hold steady at 7.0%, though again the range of forecasts covers a lot of ground sitting between 6.5% on the low side and 7.3% on the high side.

What to watch | Labour Force Survey

The compositional detail on the employment number is where our focus is for today's release. Can we see a repeat of last month's outcome where full-time employment outpaces part-time work? If that were to be the case, it would add weight to the view that the recovery could be starting to broaden out where full-time work takes up more of the running with the economy now opening up more widely. Certainly, returning full-time employment back to its pre-pandemic level is likely to be a great deal harder than it has been for part-time work. But momentum is important in how that plays out so looking for signs where this may be starting to build is key.

Sunday, December 13, 2020

ABS Household Impacts of Covid-19 Survey - November

The November edition of the ABS's Household Impacts of Covid-19 Survey was released earlier today with the main topics of interest being shopping habits, wellbeing and the use of stimulus payments. Responses were taken between 13-23 November from 3,400 households, with the ABS advising of a sampling change it has made from this survey onwards to gather responses from a much larger number of households than before. 

On shopping habits, today's survey reported there has been a sizeable shift in attitudes towards online shopping, with 33.4% of respondents saying they now prefer to do more shopping online than was the case before the pandemic emerged. The shift is being driven by the two largest states, which have also had the highest case counts during the pandemic, with Victoria recording a 42.8% increase in preferences for online shopping and New South Wales rising 35.1%. While not as pronounced, there have still been noticeable rises across the other states; Queensland 27.8%, South Australia 25.9%, Western Australia 20.6% and the rest of Australia (Tas, ACT and NT 29.7%). 


ABS retail sales data confirms these trends playing out with the online segment recording a stunning rise in its share of total turnover since the onset of the pandemic. Meanwhile, recent high-frequency data made available from some of the major banks have been showing incredible strength through the Black Friday sales period. 

In looking ahead over the summer period, the online shopping habit is likely to stick. Between November to January 2021, 22.1% said they intended on shopping online once a week, 25.5% once a month, 10.8% once over the period and 2.2% said they would shop online all or most days. All up that tallies to 60.6% of respondents that intended on doing at least some online shopping over summer, with the strongest intentions coming from the two major states with Victoria at 67.8% and New South Wales 61.4%.

To be clear, in-person shopping is still very much the preferred option. A total of 94.5% of respondents said they intended to shop in-person over the summer, albeit this is slightly lower than would be the case (97.5%) if the pandemic had not occurred. But the pandemic has had varying implications depending on the type of shopping in question. The ABS's chart (below) shows that respondents tend now to be less comfortable shopping in settings where crowds are likely to be larger and social distancing is more difficult. Respondents were asked about what would be needed to improve comfort for in-person shopping. Interestingly, the key factor was visible adherence to covid-safe practices by other shoppers such as social distancing (35%), which was placed ahead of a vaccine (20%), low daily infection rates (10%), retailers following Covid-safe protocols and an easing of restrictions (5%).   

Source: ABS

The survey provided good news regarding Australians' wellbeing. After a difficult year of restrictions and uncertainty, there are now clear signs that with the pandemic coming under control stress and anxiety levels are coming down. Relative to August, the ABS's chart below shows marked declines across a range of feelings by November. 


There seems little doubt that this better sense of wellbeing is playing into the surge in consumer sentiment that has occurred over the period, with the Westpac-Melbourne Institute Index of consumer sentiment reported to have risen to a 10-year high last week. 


Meanwhile, reflecting these developments, mobility indicators have recovered to their highest levels across the nation since the early days of the pandemic as Australians are now more able and comfortable with getting out and about after coming through earlier shutdowns. 


New insights were also available in today's survey on the use of stimulus payments. The survey compared the use of payments coming through to households via the coronavirus supplement (CS) attached to the JobSeeker support and the JobKeeper (JK) wage subsidy. 

Source: ABS 

Source: ABS 

In either situation, the top 3 uses were the same; household bills (CS 67.4% to 78.1% for JK), household supplies/groceries (CS 63.3% to 62.6% for JK) and rent/mortgages (CS 38.9% to 54% for JK). One of the key differences was in the level of saving, which was noticeably higher for CS 26.3% to 16.5% for JK. This likely reflects the finding from the survey that reported that 3 in 4 receiving the JK payments said it was lower than their usual pay. 

Friday, December 11, 2020

Macro (Re)view (11/12) | ECB extends stimulus; Australian sentiment at 10-year high

This week's long-awaited meeting by the European Central Bank's Governing Council confirmed that existing stimulus measures have been "recalibrated" to ensure the duration of support matches the projected path of the pandemic and that favourable financing conditions are maintained throughout. Backed by the optimism around vaccine developments, the ECB's updated economic projections are based on the overarching assumption that the effects of the pandemic dissipate by the end of 2021 ahead of a pick-up in the recovery in early 2022. The actions taken by the Governing Council this week had been well signaled by the ECB in the lead-up and will see the length of its pandemic support response pushed out to match this timeline. 

The headline announcement was a 500bn increase in the Pandemic Emergency Purchase Programme (PEPP) envelope to 1,850bn, with a 9-month extension to take purchases through to at least end-March 2022. Term funding to the banking sector was also expanded and the conditions made more favourable. Under TLTRO-III, the ECB will offer liquidity to the banks at a minimum rate of -1.0% for an additional 12-month period to mid-2022, with three new rounds of funding under the scheme to be made available over the second half of 2021 (with maturities of 3 years). Banks will also be able to access more funding than was previously the case, equating to 55% of their stock of eligible loans up from 50% earlier. Furthermore, the period under which the relaxed rules around the quality of collateral banks must provide to obtain the funding has been lengthened to mid-2022. The changes to the PEPP leave an important backstop in the European sovereign debt market in place for longer, keeping spreads compressed and allowing governments across the continent to keep emergency spending flowing throughout the crisis, while the TLTRO changes are aimed at ensuring ample credit supply at favourable terms to businesses and households as they confront the pandemic-induced recession. 

Data this week reported that after contracting by 15% over the first half of the year, euro area GDP had rebounded by 12.5% in the September quarter on the reopening. But this progress has since been derailed by a return to shutdown after a surge in virus cases, with the ECB forecasting a 2.2% contraction in Q4 for an overall decline of 7.3% this year. This has pulled down the outlook for GDP growth in 2021 from 5.0% to 3.9%, though as the pandemic dissipatess a stronger outcome is in place for 2022 at 4.2% from 3.2% previously. The outlook for inflation remains very subdued and was little changed overall; 0.2% in 2020, 1.0% in 2021, and 1.1% in 2022, with a lift to 1.4% in 2023 still leaving it well short of the ECB's target. With that being the case, the recent strength of the single currency has come into question, though in the post-meeting press conference President Christine Lagarde limited her remarks on the issue to noting that while the ECB does not target the level of the exchange rate it will continue to monitor it closely. 

Over in the US, cross-party negotiations towards a fiscal stimulus package continues to remain in focus with the Republicans and Democrats struggling to come to terms on support for state and local governments and for liability protections for businesses and educational institutions in the case where workers or students were to fall ill due to the pandemic. One way forward is for these two issues to be carved out of negotiations for the time being so that a package can be put together consisting of measures where there is bipartisan support for immediate assistance to be provided, though even that option is struggling to gain traction. In the meantime, there were signs in the data this week from the US that the latest surge in virus cases was taking hold in the labour market as initial jobless claims came in much higher than the markets had anticipated at 835k against an estimated 725k, while continuing jobless claims printed at 5.76m to also come in above consensus (5.21m). Meanwhile, inflation in November was subdued in holding steady at 1.2%Y/Y and at 1.6%Y/Y on the core measure (excludes food and energy prices) against expectations for it to soften slightly.  

— — 

Shifting to the Australian perspective, with last week's national accounts highlighting the importance of households in driving the economic recovery through the 3.3% rebound in GDP in Q3 (see here), data this week was supportive of the durability of that story into 2021. Speaking to this was the continuation of the strength in consumer sentiment with the Westpac-Melbourne Institute Index rising by a further 4.1% in December to 112.0 with the reading now sitting at a decade high (see chart of the week, below). The turnaround has been stunning as it has been sharp. Back in August, the index had collapsed to a reading of 79.5 as Victoria was placed back into shutdown, but as the virus came under control in the state and remained contained across the rest of the nation, the prospect of sustained reopening has fuelled the optimism with consumer sentiment surging by 41% over the period. 

Chart of the week

Very clearly, this has led to a quickly improving outlook for economic conditions by Australians with expectations for the next 12 months (+24.9%) and 5 years (+32.7%) both up sharply on a year ago. Off the back of this, the unemployment expectations index has improved significantly and is currently showing its most upbeat reading in nearly 10 years. Helped by policy stimulus, sentiment towards the housing market has accelerated over recent months with views around purchasing a dwelling and expectations for house prices sitting at elevated levels. On house prices, the ABS reported a 0.8% rebound in capital city prices in Q3 after a modest 1.8% decline during the shutdown-impacted Q2 (see here). 

A broader reopening of the Australian economy is also driving improved confidence and conditions for firms as reported this week in the NAB's Business Survey for November. In the month, business confidence jumped by 9 points to a reading of +12 to post its 4th consecutive gain, while business conditions advanced by 7 points to +9, though weakness in the employment component (-5) remains in sharp contrast to the improvements that continue to come across trading (+17) and profitability (+15), indicating that firms want to see the positive backdrop be sustained before it starts to filter through to hiring intentions. The underlying detail reflected the optimism around the reopening with almost all surveyed industries reporting gains in confidence and conditions in November, with a notable standout being the retail sector consistent with the current strength in household spending.  


Monday, December 7, 2020

Australian property prices rise 0.8% in Q3

The decline in Australian capital city property prices following the onset of the Covid-19 pandemic was confined to a 1.8% fall in the June quarter, with the ABS reporting a 0.8% rise nationally in the September quarter, according to its latest release this morning. The pace of growth through the year moderated from 6.2% to 4.5%. Prices lifted in every capital city in Q3 except for Melbourne where activity in the residential property market was heavily affected by the shutdown. The largest price gains in Q3 were in the 'second-tier' markets of Adelaide (1.6%) Brisbane (1.5%) and Perth (1.4%). 


An interesting aspect of today's report was that the turnaround in conditions in the property market may have come through earlier than previously thought. Timelier data compiled by CoreLogic had been indicating that capital city property prices declined all the way through Q3 before starting to rise from October (0.2%) and then elevating at a stronger pace in November (0.7%). 


A summary of the price changes nationally and for each capital city market in Q3 is provided in the table below. With the exception of Melbourne, house prices outperformed units in the quarter and this likely reflects the differences between the owner-occupier and investor segments of the market. A range of stimulus measures such as the HomeBuilder scheme and first home buyer supports have been shown to have had a noticeable impact on detached housing in the owner-occupier segment in particular, whereas investors that typically favour units have been confronted with elevated vacancy rates in the capital cities and this has likely been weighing on sentiment in that segment. Despite the pandemic and its broader economic impact, annual growth in prices to Q3 was positive in every market except for Darwin, which contrasts sharply with the same point in 2019 where price growth was negative through the year in all markets outside of Hobart. Notably, annual price growth in Perth (2.4%) is now at a 5-year high, while it is at 3-year highs in Brisbane and Canberra.        


For most of the nation's capital cities, the onset of the pandemic effectively brought on a pause in activity in the property market. This led to relatively modest declines in prices across the capitals, as the chart below shows. However, as restrictions were eased and following the introduction of policy stimulus, prices have started to rise again. But in Melbourne, prices continued to decline in Q3 as the shutdown there remained in place. Over the medium to longer term, the key issue that could slow the momentum and weigh on prices is low population growth if, as seems likely, restrictions on the international borders remain in place for an extended period. 

The effects of the pandemic on property prices at an aggregate level nationally and in each capital city are summarised in the chart below. In Q2, prices declined in every capital city except for Canberra due to the impact of the shutdown on property market activity, with the steepest falls coming in Syndey (-2.2%) and Melbourne (-2.3%). In Q3, prices started to rebound across the nation, though they continued to fall in Melbourne (-0.3%) after the reversal of its reopening. As a result, Melbourne prices have fallen by more over the pandemic period (-2.5%) than any other market. Relative to Q1 2020, prices also remain lower nationally (-1.0%) and in Sydney (-1.2%) and Darwin (-0.6%). In contrast, after strong performances in Q3, prices in Canberra (1.6%), Hobart (0.8%), Adelaide (0.7%), Perth (0.7%) and Brisbane (0.6%) are now all higher than they were before the onset of the pandemic reflecting the return to more normal activity and the policy stimulus impact. 

Friday, December 4, 2020

Macro (Re)view (4/12) | Australian Q3 GDP confirms reopening rebound

Australia's September quarter national accounts were the highlight from a full calendar of events over the past week. The reopening effort from the national Covid-19 shutdown generated a stronger-than-expected rebound in real GDP growth in Q3 of 3.3% (-3.8%Y/Y) as the easing of restrictions enabled household consumption to come back strongly (7.9%) after collapsing in Q2 (-12.5%) (see chart of the week). The outcome also reflected the strength of the policy response that shielded incomes from the severe dislocation that occurred in the labour market as the pandemic hit. Our feature review of the September quarter national accounts with in-depth analysis and key charts is available here.   

Chart of the week

The reopening saw households re-engaging widely in activity across the economy as services consumption lifted by 9.8% (from -17.9% in Q2) and goods consumption incresed by 5.2% (-3.4% in Q2). Key back in the September quarter - as it will be looking ahead to the time when fiscal support tapers - was the strength of household balance sheets. Real growth in household disposable income lifted a further 3.3%q/q  from 3.5% in Q2, lifting the pace through the year to a 12-year high at 7.6%. Together with the earlier impact of the restrictions, household saving soared up in Q2 to 22.1% before declining fairly modestly to a still very elevated level at 18.9% in Q3. This indicates households retain plenty of scope to put towards consumption down the track as conditions in the economy normalise further and emergency supports are withdrawn. 

The effect of policy stimulus also flowed through to dwelling investment (0.6%q/q) as a 5.1% rise in alteration work in response to the HomeBuilder scheme was able to overcome a 9th straight quarterly decline in new home building (-2.1%). Given the level of uncertainty around the economic outlook, business investment was understandably weak again (-4.1%q/q), though the authorities will be looking for the measures contained in the recent Federal Budget around expanded asset write-offs to be gaining traction towards the end of the year. Meanwhile, net exports weighed sharply on growth in the quarter (-1.9ppts) driven by a 6.5% lift in import volumes as domestic demand conditions improved on the reopening. Public demand continued to be a support for the economy led by consumption spending to be up by 6.2% through the year, contrasting sharply with the weakness in private demand (-6.7%Y/Y). 

After contracting by 7.3% over the first half of the year, Q3's 3.3% rebound still leaves Australian GDP 4.2% below its pre-pandemic level. Meanwhile, hours worked remain 7% down on their end-2019 level reflecting the impact of elevated spare capacity in the labour market. While the recovery to date has been stronger than expected, the RBA emphasised at this week's Board meeting where policy settings were left unchanged (see here) and then at its appearance before the House of Representatives Economics Committee that it was still likely that the remaining progress would be "uneven" and "drawn out". While RBA Governor Philip Lowe highlighted that there was reason to be optimistic on the outlook given the building momentum in the economy and potential vaccines on the horizon, the reality was that the nation was "likely to experience a run of years with unemployment too high and wage increase and inflation too low". As such, the RBA expects it will not be increasing its rates structure for at least 3 years, while it will also be keeping its bond purchase program "under review".

Details from the other key data points out during the week were upbeat. Indicators on the housing market continue to flash green on the support of policy stimulus measures; dwelling approvals surprised to the upside lifting by 3.8% for the month in October with detached house approvals at a 20-year high (see here), housing finance commitments extended their recent surge since the reopening with a 0.7% rise in October (see here), and house prices nationally according to CoreLogic increased for a second straight month with the pace rising to 0.8% in November from 0.4%. On the household consumption story, October's retail sales report was potentially a sign of things to come as a 5.1% reopening rebound in Victoria lifted national turnover by 1.4% in the month (see here). Lastly, the trade surplus widened to $7.5bn in October as a monthly record on the value of iron ore shipments drove exports up by 5.4% (see here). 

— — 

Turning to developments abroad, the reflation theme was the main influence in markets as recent weakness in the US dollar broadened out and was sustained throughout the week, with the US Treasury yield curve steepening on rising inflation expectations. Resonating here was the idea that positive news on vaccine developments could help achieve wider and more sustained reopening of economies, while there was renewed optimism around prospects for Congress to come to terms on a fiscal stimulus package with the Democrats scaling down their base for negotiations with the Republicans from $2,400bn to around $900bn. Market expectations for more fiscal stimulus were enhanced by Friday's US labour market report where employment on nonfarm payrolls was considerably weaker than forecast in November at 245k against the consensus estimate of 469k. There was a slight move lower in the unemployment rate fell from 6.9% to 6.7%, though this came alongside a decline in the participation rate (-0.2ppt) to 61.5% as more people left the labour force. A new fiscal stimulus package would help to support the recovery in the economy and this reinforces the optimistic narrative in the markets. A steeper US Treasury yield curve has prompted speculation that the Federal Reserve might look to cap the rise by shifting the focus of their asset purchases out to longer-dated maturities. There was little insight on this issue from Federal Reserve Chair Jerome Powell as his Testimony appearance this week, other than the commitment that asset purchases would be left in place until such a time that it was no longer required. 

Meanwhile, over in Europe the appreciation of the single currency against the dollar to its highest level since April 2018 has been the focus of attention ahead of next week's policy meeting by the European Central Bank. At its previous meeting, the ECB's Governing Council pledged to "recalibrate its instruments" to keep financial conditions favourable following the recent setback to the economic recovery from the reinstatement of shutdowns to curb the spread of the virus. Expectations are, therefore, elevated going into the meeting, with a Bloomberg report indicating that the Governing Council might be leaning towards agreeing to a 12-month extension of its pandemic emergency purchases programme out to mid-2022 and potentially increasing its size by €500bn from 1,350bn currently. Commentary from ECB officials has also indicated that additional support via the TLTRO (cheap funding to the banking sector) scheme is likely. Here, the current iteration of the TLTRO scheme has a special discount period in place where banks can obtain funding from the ECB at a rate up to 50bps below the deposit rate (currently -0.5%) between mid-2020 to mid-2021, depending on their lending activity. Speculation is that the availability of the minimum -1.0% TLTRO rate will be extended by 12 months to mid-2022.   

Thursday, December 3, 2020

Victoria drives Australian retail sales higher in October

A Victorian-driven rebound in spending towards the end of the state's shutdown saw Australian retail sales 1.4% higher in the month of October. The result was a touch weaker than expected (1.6%), but the level of turnover remains elevated having been supported by the momentum generated by the reopening of the economy that was reported in this week's national accounts for Q3 (see here) and by significant policy stimulus measures.  

Retail Sales — October | By the numbers 

  • Retail turnover (nominal) advanced by 1.4% in October to $29.552bn, coming in a touch weaker than the preliminary and market estimate of 1.6%, after falling by 1.1% in September. 
  • Annual growth in retail turnover lifted from a 5.6% pace to 7.1%.


Retail Sales — October | The details  

National retail sales lifted by 1.4% overall for the month in October, with the key driver being a 5.1% rise coming through in Victoria (-5.8%yr) as the state started to reopen from its second pandemic-induced shutdown. Turnover growth across the rest of the nation steadied with a 0.3% rise in October, coming off a 1.3% fall in the month prior.


Overall, the level of retail sales remains elevated at around 6.4% above their pre-pandemic level reflecting the reopening effort and a very strong stimulus response that has boosted disposable incomes, while the pandemic itself has also brought on shifts in consumption patterns with a greater share of consumption going into goods away from services due to the restrictions. 


Across the categories, the strongest gains came from clothing and footwear (6.8%mth) and cafes, restaurants, and takeaway food (5.4%mth), both of which received a reopening boost from Victoria where clothing and footwear sales surged by 41.7% and cafes, restaurants, and takeaway food increased by 14.9%.     


Comparing turnover levels, the chart below highlights that the pandemic has had an uneven effect across the sector with the restrictions benefitting some areas (online, household goods, food) and hurting others (clothing and footwear and cafes, restaurants and takeaway food and department stores). 


As previously highlighted, Victoria led the way in October with turnover in the state up by 5.1% compared to a 0.3% rise across the rest of Australia. This has put the recovery in Victoria in motion, but if the other states are any guide, there is reason to think that this is only just getting started. Retail turnover in Victoria is 7.1% below its pre-pandemic level whereas it is up by 11.3% across the rest of Australia over the period. Furthermore, high-frequency card data from some of the major banks have been showing that retail spending in Victoria has been very strong in November. 


Retail Sales — October | Insights

Victoria's 5.1% lift in the month should be a sign of more to come and this is likely to help keep retail spending nationally elevated. The other factors going for retail at the moment are ongoing policy stimulus, very strong activity in the detached housing market, wider reopenings with some earlier restrictions on interstate travel being unwound recently and strong consumer sentiment as immediate concerns around the pandemic have dissipated on a low case count. However, these effects could see growth in retail sales could come back a little if it encourages more spending in services areas of consumption that were previously restricted or avoided.     

Australia's trade surplus widens to $7.5bn in October

Australia's trade surplus widened more sharply than expected in October to $7.465bn, taking it back to its level from mid-year. The key was a strong advance in export earnings as the value of iron ore shipments hit a record high while imports were broadly stable after falling noticeably in the month prior. 

International Trade — October | By the numbers
  • Australia's trade surplus increased by $1.641bn in October to $7.456bn, well clear of the median estimate situated at $5.8bn. September's initially reported surplus of $5.63bn was revised up to $5.82bn. 
  • Export earnings advanced by 5.4%m/m to $35.72bn following on from a 2.6% rise in September (revised from 3.9%), slowing the annual decline to -11.7% from -20.2%. 
  • Imports consolidated with a modest 0.6% rise to $28.26bn after contracting by 6.5% in September, leaving the annual pace at -21.3% from -22.2%.  


International Trade — October | The details

The nation's trade surplus had stepped lower since June reflecting a rise in imports as domestic demand conditions improved on the reopening of the economy. It then lifted in September as import spending pulled back and exports increased modestly. As export earnings improved at a faster pace in October, the trade surplus has been restored to around its level from mid-year. 

On the export side in October, earnings increased by 5.4% to $35.72. Driving this was an 8.4% rise from non-rural goods (-2.1%yr), which boosted earnings by $1.94bn as the export of metal ores and minerals (predominantly iron ore) elevated by 14% to a record high level ($13.97bn). The ABS's detailed breakdown indicated this mainly reflected increased shipment volumes. Rural goods increased by 8.2% in the month ($0.26bn) on broad-based gains across the category. Volatile non-monetary gold pulled back this month (-16.1%) after surging by nearly 72% in September. In services, earnings were 0.5% softer at $5.18bn after falling precipitously earlier in the year on the introduction of the international border closure to help contain the pandemic. 


For imports, total spending was a touch firmer in October rising by 0.6% ($0.18bn) to $28.26bn (-21.3%yr). All categories increased but the gains were modest with consumption up 1.6% support by new vehicles, capital goods 1.6% higher on telecommunications equipment and intermediate goods posting a 1.7% lift. Services imports were little changed (0.4%) and remain around their level from earlier in the year after the introduction of the overseas travel ban saw spending in the category plunge.  


International Trade — October | Insights

The month to month trade flows remain volatile during this pandemic episode. Over September-October, the trade surplus lifted by $4.44bn, but in the two months prior to that period it fell by $4.38bn. Import spending rebounded on the reopening of the economy and this was reflected by net exports subtracting 1.9ppts from GDP growth in yesterday's national accounts for Q3 (see here). Today's report pointed to a moderation in import spending with exports starting to pick up.