Independent Australian and global macro analysis

Friday, July 9, 2021

Macro (Re)view (9/7) | Shifting expectations

The all-important July RBA Board meeting had something for everyone this week, with the first steps towards policy normalisation coming as the expectation for rate hikes to commence earlier than 2024 was reaffirmed as unlikely. Despite the uncertainties associated with the recent virus outbreaks and lockdowns, the resilience of the economy to rebound from similar setbacks throughout the pandemic and the pace of progress seen to date in both employment and output has the RBA sufficiently confident that the transition from recovery to expansion remains on track. This assessment has prompted a recalibration of policy, with the direction now shifting towards tighter rather than easier settings. On this week's decisions, the Board decided not to extend the maturity of the yield target, retaining the target bond at the April 2024 AGS issue, while QE purchases are to be dialed back slightly from early September where the current pace of $5bn per week will ease to $4bn (reviewed here). The non-extension of the yield target had been expected by markets but the decision to signal the start of tapering had been at the more hawkish end of forecasts going into the meeting.

As discussed by Governor Philip Lowe in Tuesday's post-decision press conference, the overall monetary policy stance has been recalibrated to reflect the shift in expectations for the economic outlook. While the Board continues to assess the economy as being unlikely to be in a position where rate hikes can commence earlier than 2024, it also acknowledges there are other possibilities here. This was the basis for not extending the yield target, meaning that instead of rolling over the signal to keep rates at 0.1% for the next 3 years, the commitment gradually declines as we approach April 2024. Key for the RBA remains the outlook for the labour market, with expectations for wages growth still seen as being inconsistent with meeting the inflation target earlier than its 2024 guidance. Going into greater detail in a separate speech, Governor Lowe pointed to the responsiveness of labour supply to meet increases demand as contributing to slow wages growth over recent years. While the onset of the pandemic and travel restrictions have clearly affected one of the channels of labour supply, the RBA had not seen evidence that higher wages in areas where there was a shortage of skills would broaden out across the economy. As such, with a tight labour market remaining its focus, the Board opted to expand QE purchases beyond early September and has committed to keep doing so until it has seen "further material progress" towards its inflation and employment goals. But QE purchases are set to take on a more nuanced approach from current parameters. Firstly, there is to be a reduction in the run rate to $4bn/wk from $5bn, a modest tapering signal (see chart below) reflecting the progress already achieved in the recovery, and secondly, the pace will come under review periodically as the economic conditions evolve. Initially, this course has been committed to from early September through to the November Board meeting, which will result in a further $42bn of purchases on top of the $200bn that will have been completed by that stage. 

Chart of the week

To this week's data releases where there was an upwardly revised final estimate for national retail sales, rising by 0.4% for the month of May against a broadly flat (0.1%) preliminary reading (reviewed here). Victoria's recent lockdown induced significant volatility into the result, reflected in the composition of spending growth nationally with strength in food retail (1.1%m/m) offsetting weakness in discretionary categories (-0.1%m/m). Further volatility will come through in June and July reflecting more lockdowns, but retail spending still remains elevated, standing 12.2% above pre-pandemic levels. Dwelling approvals posted a second consecutive sharp monthly fall with a 7.1% decline in May, centered on weakness in the detached segment (-10.3%m/m) that reflected the unwinding effect from the recently expired HomeBuilder grants scheme (reviewed here). 

— — 

Moving offshore where reflation trades have continued to come under pressure, with the flattening in yield curves ramping up debate over the catalyst. On the one hand, positioning squeezes and significant central bank purchase programs are put forward, but on the other is the sentiment that growth and inflation expectations have seen their peaks and are now set to decelerate. That debate will roll on, but there was little new information for markets to factor in this week other than the ongoing concerns with the Delta strain and perhaps a shift in perceptions of the recent Federal Reserve meeting. The minutes from the FOMC's June meeting put a slightly different spin on the widely hawkish interpretation taken at first glance. The updated summary of economic projections showed that the median expectation for rates had brought forward two hikes into 2023 but the meeting minutes did not appear to completely vindicate the sense that policy tightening would be hastened. Coming well before any rate hikes will be the tapering of QE purchases from the current pace of $120bn/mth, but the threshold for this to occur has yet to be met and as several of the Committee members noted was still far from doing so. With the "substantial further progress" towards its employment and inflation goals yet to materialise, the patient approach being taken to tapering seems likely to continue. Thus the emphasis is on the data flow over the near term, with next week's CPI inflation report for June the highlight event on next week's calendar. 

Over in Europe, the ECB tabled its long running strategy review into the conduct of its monetary policy. The outcome was as had been widely touted in recent weeks with a modification being made to its inflation target from "below, but close to, 2%" to a symmetric 2% target over the medium term. In practical terms, this change is a tilt towards a more dovish structure in that it will permit the Governing Council to tolerate a period of overshoot in inflation, in turn allowing other macroeconomic objectives such as full employment to be prioritised. But it stops short of shifting to the Average Inflation Targeting regime of the Federal Reserve, in which policy is set in such a way to generate overshoots to make up for earlier periods where inflation was too low. As it currently stands, the ECB's projections for inflation sit below target this year (1.9%) and in 2022 (1.5%) and 2023 (1.4%). Also from the ECB this week was the account of the June policy meeting. The consensus among the Governing Council was to continue with purchases under the PEPP program at their accelerated pace over the current quarter to preserve favourable financing conditions over the summer months. However, of interest was the line that some members had argued for the pace of purchases to be tapered to reflect an improved growth and inflation outlook. Surprising to the upside this week was May's reading on euro area retail saleswhich came in at 4.6% for the month (vs 4.3% expected) to be up by 9.0% over the year (vs 8.2%). This was driven by a surge in non-food sales volumes (8.8%mth) as the easing of restrictions saw consumer demand rebounding very strongly from a weak result in April.

Tuesday, July 6, 2021

RBA QE to taper; yield target maturity retained

The recalibration of the RBA's monetary policy settings announced today were broadly as markets had anticipated, though the decision to signal the start of tapering in early September was at the more hawkish end of forecasts for the July meeting. As noted in the preview, the key theme the RBA has been keen to put forward of late is the transition taking place in the economy from recovery to expansion and this has had implications for policy. To summarise today's announcements, the maturity for the yield target was retained at the April 2024 bond, while QE purchases will reduce in pace from the current weekly run rate of $5bn to $4bn once the second $100bn tranche of purchases is completed in early September. The target for the benchmark interest rate and 3-year AGS yield was unchanged at 0.1%. Overall, the main takeaway continues to be that the Board assesses the economic outlook as being unlikely to prompt rates hikes before 2024 due to subdued inflation and wage dynamics. 


Today's decision statement from Governor Philip Lowe outlined that while the rebound in the Australian economy from the pandemic crisis has been stronger than expected and future prospects remain positive, the recovery was still in need of significant monetary stimulus with the latest setbacks from outbreaks and lockdowns a reminder of the risks still present. The net result of this assessment was that the Board elected not to extend the yield target to the November 2024 bond, keeping the focus of the policy at the April 2024 line. This prompted a slight tweak in forward guidance, though the message largely remains the same with rate hikes not anticipated "before 2024" compared with "until 2024 at the earliest" previously. Governor Lowe expanded on this timing in a special post-meeting press conference, noting that while employment and GDP had seen strong recoveries from the depths of last year, the nominal side of the economy, namely in inflation and wages growth, had lagged in this upswing. Prior to the pandemic, inflation in Australia had been below the RBA's 2-3% target for several years and wages growth had been on a downward trend. Powerful structural headwinds are seen to have contributed to this, and while these still persist, the RBA believes the key to breaking this cycle is a tight labour market to drive wages growth above 3%. But this is expected to be a drawn-out process and this is reflected in the Board's 2024 guidance. Despite yields at the 3-year segment sitting above the 0.1% target, there was no sign that the RBA is readying to step back into the market here but it "remains prepared" to do so and the case to respond could build if the global shift higher in front-end rates is sustained.

On its QE program, the RBA signaled today that in early September the pace of purchases will taper as it shifts to a more flexible set of parameters than currently in place. With the flow of economic data to be key to determining the run rate, the signal to reduce purchases from $5bn per week to $4bn was justified in the decision statement as reflecting the strength of the recovery and positive outlook. Understandably, Governor Lowe was keen to emphasise that the taper did not constitute a withdrawal of support. While a more flexible approach to bond-buying was widely expected, the taper signal did come as a surprise (I had expected purchases to stay at $5bn per week) given the non-extension to the yield target and the recent expiry of the Term Funding Facility. This also comes ahead of the US Federal Reserve outlining its plans for tapering. Nonetheless, it is a modest tapering plan, with the technical details showing that Commonwealth Government purchases (Mondays and Thursdays) are to ease from $2bn to $1.6bn, while semis purchases (Wednesdays) slow to $0.8bn from $1bn. This still retains the existing 80/20 split by which purchases have been accumulated to date. The RBA has committed to this course from early September until the November meeting when the pace of purchases will next come under review, which implies a tranche of a little more than $42bn. However, purchases will almost certainly be extended beyond this timeline, with Governor Lowe outlining that bond-buys will continue "until there is further material progress towards the goals for full employment and inflation". 

Monday, July 5, 2021

Preview: RBA July meeting

The Reserve Bank of Australia Board meets today where it will recalibrate the settings for its 3-year yield target policy and bond purchase program. At 2:30PM, the decision statement from Governor Phillip Lowe will confirm the changes, with a special press conference at 4:00PM to provide further insights (times are AEST). The target for the benchmark interest rate will remain at 0.1%, while the access window for drawdowns under the RBA's Term Funding Facility has now closed after it expired at the end of June.


Since the previous meeting, the main theme in the RBA's communications has been the transition underway as the economy progresses from recovery to expansion. Given the latest setbacks from the pandemic, prompting a return to lockdowns and tighter restrictions in several major cities, as well as slow progress in vaccinations, the renewed uncertainty places added emphasis on how today's changes are communicated, though it appears unlikely to be enough to delay a slight reduction in policy accommodation. The recovery to date has exceeded the RBA's expectations and the Board now sees an unemployment rate back to where it was prior to COVID at 5.1%, while employment and economic output have rebounded to pre-pandemic levels. 

The RBA's forward guidance on rates has been that the conditions that would justify hikes are unlikely "until 2024 at the earliest". Reinforcing this has been the 3-year yield target, which is currently aimed at holding yields on April 2024 AGS at around 0.1%. Today's meeting will give a decision on whether the target remains at the April 2024 bond or is extended to the next maturity, being the November 2024 line. Market consensus is for no extension and it appears likely the RBA will meet this expectation. As has become clear in recent communications from the Bank (June minutes and Governor Lowe speech on June 17), key to the decision is an assessment of the prospects for the economic conditions to be sufficient to justify a rise in the cash rate at some stage over the next 3 years. With this clarification and given the strength of the recovery, it is likely that the Board will assess that they have sufficient confidence that inflation will be within the 2-3% target and the labour market at full employment with higher levels of wages growth (around 3%) by 2024. The 3-year AGS yield has recently been trading above the 0.1% target, with the catalyst being the hawkish interpretation markets took from the latest US Federal Reserve meeting, as front-end rates repriced higher in anticipation of an earlier start to its hiking cycle. It would not surprise if the RBA uses this juncture to at least signal to the markets that it is prepared to restart its 3-year purchases to keep yields closer to the 0.1% target. With the yield target still in place, this suggests no change to the RBA's forward guidance on rates.    


With regards to the bond purchase program, the RBA is currently adding to its balance sheet $5bn of Commonwealth and state and territory government bonds (with maturities of between 5 and 10 years) per week in an "80/20" split. Purchases commenced after the November 2020 Board meeting when an initial $100bn tranche was announced over a 6-month period. A second $100bn tranche was then announced at the Board's meeting in February, and with these purchases starting in April they are on track to be completed by early September. Today's decision will inform us of the parameters purchases will take after this. Options the Board has under consideration include maintaining the status quo ($100bn over 6 months), a tapered approach where either the size of purchases is reduced or the timeline for those purchases is lengthened (resulting in a lower weekly pace of purchase), or shifting to a flexible structure where the pace of purchases is reviewed more frequently and can be adjusted to changes in the underlying economic conditions. My expectation is for a shift to the flexible option, with a plan for open-ended purchases to be announced, starting at the current pace of $5bn per week (in the "80/20" split). Reviews regarding the pace of purchases can be conducted to coincide with the release of the Bank's quarterly Statement on Monetary Policy, where the Board can use updated economic forecasts to help explain changes. 

The tapered approach seems less likely in the circumstances. Signaling tapering stikes as too hawkish a response coming on the back of the expiry of the Term Funding Facility, as well as the expected non-extension to the 3-year yield target. With the Federal Reserve yet to outline its plans for tapering, such a move by the RBA risks tightening financial conditions through a higher exchange rate and higher bond yields. The recent setbacks with the virus domestically and also employment and inflation still short of the RBA's goals also argue against any tapering signal at this point.

Australian dwelling approvals fall 7.1% in May

Australian dwelling approvals posted a second consecutive sharp month-on-month decline with a 7.1% fall coming through in May. This followed April's 5.7% contraction, though whereas that outcome was driven by weakness in the higher density segment, May's fall was driven by an unwind in house approvals following the recent expiry of the HomeBuilder grants scheme.

Building Approvals — May | By the numbers
  • Dwelling approvals (seasonally adjusted) declined by 7.1% in May to 20,163, falling by more than the 5.0% decline expected by markets. Approvals fell by a revised -5.7% in April from -8.6% reported initially. Annual growth in approvals lifted to 52.7% from 42.4% on base effects. 
  • House approvals rolled over from a record high level, falling by 10.3% in the month (prior 5.0%) to 13,664 to be up by 53.6% over the year.
  • Unit approvals were broadly unchanged in May ticking up by 0.7% (prior -24.0%) to 6,499. This stands 51.0% higher than a year earlier.


Building Approvals — May | The details 

The sharp 7.1% fall in headline dwelling approvals in May was driven by the lower density segment as house approvals contracted by 10.3%mth. The details were consistent with the response from the recent expiry of the HomeBuilder scheme to new applicants at the end of March. The scheme initially offered grants of $25k towards new builds (and renovations) provided certain income and price caps were met, then at the start of the year the grants lowered to $15k but with some adjustments to the price caps depending on the location. With the grants closing at the end of March, house approvals are now unwinding from record high levels. The scheme has proved highly stimulatory and has brought forward a significant volume of house approvals in particular. 


Approvals for alterations also surged to record highs following the inception of HomeBuilder, but this too is now also starting to unwind with the value of these approvals falling by 12.7% in May to $0.95bn (39.0%yr). 


The state data also confirms the HomeBuilder unwinding effect, with house approvals down sharply across all states in May. The sharpest declines were in May were in Western Australia (-17.7%), South Australia (-17.0%) and Queensland (-14.0%), states that all saw a very strong elevation in detached approvals.   


Building Approvals — May | Insights 

The weakness in May is likely a sign of things to come in the dwelling approvals data, particularly in the detached segment with the support of HomeBuilder now expired. While the scheme has brought forward a high volume of house approvals, there remains uncertainty over how long the upswing in residential construction activity could last beyond 2021. 

Australian retail sales rise 0.4% in May

Australian retail sales printed at a stronger-than-expected 0.4% in May, outpacing the initial estimate that reported a 0.1% lift. The decline in sales in Victoria (-0.9%) associated with the state's recent lockdown was less severe than the 1.5% fall in the preliminary estimate. Retail spending remains elevated, up 7.7% over the year and 12.2% above its pre-pandemic level.  

Retail Sales — May | By the numbers 

  • National retail turnover lifted by 0.4% in May to $31.16bn, coming in ahead of the preliminary estimate for a 0.1% rise. Turnover in April advanced by 1.1%. 
  • Annual turnover growth stepped down from 25.0% to 7.7%, as base effects from the early stages of the pandemic played through. 


Retail Sales — May | The details  

National retail sales lifted modestly in May (0.4%) around a lot of volatility associated with Victoria's recent snap lockdown. As the state went into lockdown, basic food sales surged, up 3.7%mth, and with non-essential retail shuttered, sales ex-food plunged by 3.8%mth. This was the driving factor behind the composition at the national level in which basic food showed strength (1.1%mth) as discretionary categories (sales ex-foods) softened (-0.1%mth). Household goods (-1.1%) and department stores (-0.7%) showed the most weakness nationally, driven by significant declines in these categories (-4.9% and -11.1% respectively) in Victoria. Given the composition of spending in May reflected a stay-at-home mix, the weakness in online retail sales (-4.8%mth) was somewhat surprising.  


Looking through these effects, monthly turnover remained at a very elevated $31.16bn in May, up 7.7% on a year earlier when the national reopening was underway and 12.2% above pre-pandemic levels. Discretionary sales have driven the upswing, rising to be 14.5% higher than in May 2020 and a touch stronger (14.8%) against their pre-pandemic level.  


Turning to the states where, as discussed, Victoria (-0.9%) was the major headwind to retail sales in May. However, this was overcome by strong gains in the month in Queensland (1.6%) and Western Australia (1.3%), as well as a more modest uplift in New South Wales (0.5%). As the chart (below) shows, spending in all states was comfortable above pre-pandemic levels in May. But it is worth highlighting that Victoria has underperformed the other states having been most affected by lockdowns. 


Retail Sales — May | Insights

Today's report broadly showed the impact of Victoria's most recent lockdown weighing on national retail turnover in May. Spending in Victoria will rebound in June as the state reopened, but more volatility will hit the data next month with Sydney, Brisbane and Perth having gone into lockdowns after virus outbreaks.

Friday, July 2, 2021

Macro (Re)view (2/7) | Recoveries and setbacks

The spread of the Delta variant of Covid-19 cases that led to the lockdown in Sydney broadened out to lockdowns in several other major Australian cities over the past week, some of which are now easing. Caseloads nationally averaged 34 per day over the 7 days to June 30, but with only around 6% of the population fully vaccinated, the public health authorities have mandated tighter restrictions to curb transmissions. In looking ahead, the plan agreed by National Cabinet on Friday proposes for precautions and restrictions to become less stringent as vaccination rates rise. Throughout the pandemic, snap lockdowns have not derailed the recovery as activity typically rebounds very quickly on reopening, though the sheer size of the Sydney economy means that the lockdown there has the potential to weigh more substantially at the national level the longer it is required to be kept in place. It should be noted that official forecasts (including by Treasury and the RBA) factor in the impact of lockdowns, conditioned on outbreaks being small and the period of hard restrictions short. Thus it appears unlikely the situation will alter the course for next week's crucial RBA meeting. But with the Board widely expected to remove some of its accommodative policy by not extending the duration of its 3-year yield target past the April 2024 bond, it will clearly want to find the right tone on Tuesday. The main message from the RBA since the previous meeting has been the transition in the economy from recovery to expansion, but as this latest setback highlights, progress is not always smooth. An expansion in the RBA's bond purchase program is also expected, which is likely to include more flexibility with regard to the pace of purchases as underlying economic conditions evolve.     

Data releases through the week remained strong, supportive of the momentum the economy was running with prior to these recent virus setbacks. The housing market remains a case in point, with robust conditions continuing as policy stimulus drives buyer demand while stock available on the supply side remains tight. Nationally, house prices according to CoreLogic's monthly index showed another elevated gain rising by 1.9% in June, albeit softening from the 2.2% rise in May. This lifted annual growth in house prices to their fastest pace since April 2004 at 13.5%. While growth in house prices remains strong, there were some signs of cooling in certain markets and segments. Prices in Perth (0.2%mth) and Darwin (0.8%mth) were much slower than in the other capitals, while price growth in the high end of capital city markets (top 25% of house prices) decelerated by more than in the middle and lower tiers, easing by 1.2ppts to 8.0% for the 3-months to June. Meanwhile, the spread in the outperformance of regional markets (17.7%yr) to capital city markets (12.4%) remains, but it is tighter than earlier in the pandemic. While demand has been supported by a range of stimulus measures, CoreLogic highlighted the effect tight supply was playing in the current price upswing. The group estimates there were around 126k new listings that came onto the market for the 3-months to June, but this was outpaced by sales transactions of around 167k over the period. With sales exceeding supply a persistent trend year to date, CoreLogic noted that the level of advertised stock was currently sitting 25% below its 5-year average. 

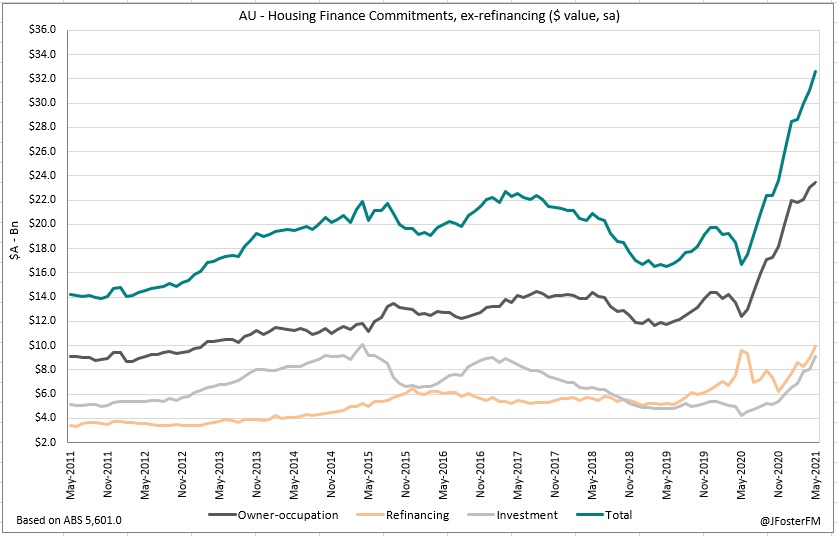
On the demand side, May's housing finance update reported a stronger-than-expected rise in commitments of 4.9%, taking growth over the reopening period to 95.4% above the trough during the national lockdown 12 months earlier. Increasingly evident is the strength in investor commitments, which surged by 13.3% in May to a near 6-year high, compared to a 1.9%m/m rise from owner-occupiers. The investor segment has had a more delayed rebound than owner-occupiers, but their presence is increasing the longer the upswing in house prices extends and as first home buyer activity moderates following the expiry of the HomeBuilder scheme (discussed in detail here). The last piece to this is the impulse the rebound has given to housing credit growth, which in annual terms has lifted from a pre-pandemic pace of 3.1% to 4.8% in May. Over the period, annual credit growth to owner-occupiers has risen from 4.9% to 6.6% and from 0.1% to 1.6% in the investor segment.  

News on the labour market extended the optimism coming out of May's very strong employment report. Job vacancies tracked by the ABS have surged to record highs rising by 23.4% for the 3-months to May at 362.5k to be 57.4% higher than pre-COVID levels (see chart below). Clearly, the demand for labour is strong and the good news is that it is broad-based in sectors across the economy, with vacancies relative to pre-COVID levels up 84% in household services, 63% in the good-related sector and 27% higher in business services. While this an encouraging sign for the outlook for employment growth and should lower unemployment further, it was covered in last week's review that 27% of businesses were finding suitable labour difficult to come by due to a lack of applicants, skills mismatches or because of the travel restrictions. Also this week, Australia's trade surplus widened in May, missing expectations but still coming in at an elevated $9.7bn (reviewed here). Exports advanced by 6.1%mth, with iron ore and rural exports reaching record highs, outpacing a 2.9%mth lift in imports.

Chart of the week 

— — 

Dominating the focus for offshore markets all week was Friday's US labour market update for June. While the report contained some strong elements, it did little to suggest that the "substantial further progress" the Federal Reserve wants to see in the recovery was near to being achieved. Employment on non-farm payrolls increased by 850k in June to outperform the median estimate for a 720k rise, while revisions to the prior two months added on a net 15k. This brought total employment to 145.8m, which is still around 6.8m below its pre-pandemic level. On the disappointing side was a slight uptick in the unemployment rate from 5.8% to 5.9% (vs 5.6% expected), while there was no change in the level of labour supply as the participation rate held steady at 61.6%, remaining well short of its level just north of 63% before the pandemic swept through. Overall, the US labour market is still very much in recovery mode with much happening beneath the surface. Employment continues to rise — June's 850k lift was the strongest outcome in a single month since last August — as vaccinations allow a wider reopening, though there are still significant hurdles in the way of people returning to work given the much lower level of participation. Another highlight in the US this week was the strong read on manufacturing conditions in June's ISM survey. Sector-wide activity levels softened slightly from 61.2 to 60.6 but are still at a highly expansionary level as the reopening continues to drive strong demand across a wide range of industries. As capacity struggles to meet this demand, bottlenecks through the supply chain remain evident. Higher prices have been the result with a further lift of 4.1ppts coming through in June taking the sub-index to its highest level since 1979. Another feature was that delivery times from suppliers became more lengthy, deteriorating by 3.7ppts in the month.     

In Europe this week, the dovish messaging from key ECB officials continued as the latest inflation data came in close to expectations. CPI inflation in June was a touch ahead of consensus on the monthly pace at 0.3%, though the annual rate eased from 2.0% to 1.9%. But this includes the boost from the rebound in global energy prices (12.5%yr). Excluding this and other more volatile prices, core CPI is up only 0.9% over the year. Though inflation is set to rise further, the ECB expects this will prove transitory, allowing its very accommodative policy settings to remain in place. This currently includes asset purchases under its PEPP program running at an accelerated pace, reaching their fastest weekly net pace (for the week to June 25) since the depths of the pandemic at 24.3bn. In the UK, the Bank of England is also taking a similar view to the inflation outlook to that of the Fed and ECB, with Governor Andrew Bailey outlining in a speech this week that it is important that the MPC does not overact to temporarily strong growth and inflation rates by prematurely tightening policy as the recovery progresses. However, Governor Bailey also noted that the Bank needed to be alert to signs that indicate higher prices could be more persistent such as high savings driving consumer spending by more than expected, wage rises emanating from a tight labour supply, and inflation expectations drifting above the MPC's target. For the time being, the recovery in the UK still has a long way to go after the return to lockdown set back real GDP by 1.6% over Q1, leaving economic output 8.8% below its pre-COVID level.


Thursday, July 1, 2021

Australian housing finance rises 4.9% in May

Australian housing finance commitments came in stronger than expected in May rising by 4.9% on the back of accelerating activity from the investor segment. Activity from owner-occupiers remains at elevated levels, though it is a nuanced picture in this segment between upgraders and first home buyers, with the latter seeing a reduction in stimulus from the end of the HomeBuilder scheme and house prices now sharply higher than at the time of the reopening a year ago. 

Housing Finance — May | By the numbers
  • Housing finance commitments ($ value, ex-refinancing) lifted by a stronger-than-expected 4.9% for the month in May to $32.6bn compared to the median estimate for a 1.8% rise. Annual growth accelerated from 68.2% to 95.4%, noting that the base period dates back to last year's trough amid the national lockdown and before many of the stimulus measures had been announced. 
  • Owner-occupier commitments increased by 1.9% in the month to $23.4bn to be up 88.4% over the year. 
  • Refinancing by owner-occupiers jumped 11%m/m to $9.9bn (2.7%yr). 
  • Investor commitments surged 13.3% in May $9.1bn (116%yr), reaching its highest level since June 2015. 


Housing Finance — May | The details 

Housing finance commitments have continued their reopening-driven upswing with a further 4.9% lift coming through in May. In the reopening period, monthly growth in commitments has averaged 5.8% and there has only been one decline over this stretch, with that being October's very small contraction (-0.1%). With significant stimulus measures introduced to support the housing market, including further cuts to official interest rates, the HomeBuilder scheme and state government incentives for first home buyers, housing commitments have risen from a national lockdown low of $16.7bn to $32.6bn as of May 2021, equating to growth of 95.4%. 


Through the first two-thirds of the reopening period, owner-occupiers were driving the upswing with the stimulus measures being targeted at that segment, in particular first home buyers. With some of these measures now having wound down and with house prices having risen sharply, the driver of the cycle has pivoted to the investor segment. An improvement in conditions in many capital city rental markets is another key factor to highlight here. 


In the owner-occupier segment, activity from 'upgraders' is continuing to rise (+3.6%mth, 95.4%yr) though commitments to first home buyers have plateaued (+2.5%mth), albeit at a very high level (+81.8%yr). Higher house prices leading to affordability concerns is likely to now be weighing on first home buyer activity. 


The other factor behind the pivot from owner-occupiers to investors as the driver of the cycle is the expiry of the HomeBuilder scheme to new applicants at the end of March. Construction-related commitments (for new builds and to purchase newly built homes) made to owner-occupiers have rolled over from a peak of $5.7bn in February to $4.7bn in May. Loans for new construction have driven this, falling from $4.2bn to $3.1bn over the period. 


The owner-occupier approvals data (by the number of commitments made rather than the value) reflect the themes discussed above. Construction-related approvals are now in decline, reflecting the unwinding of the 'frontloading' effect from the HomeBuilder scheme, while first home buyer approvals are coming down from their peak. However, set against this is the ongoing rise in approvals to 'upgraders', with higher house prices, strong household balance sheet and low rates enabling this group to remain very active in the market.  


A summation of developments across the states is provided in the table below. Comparing the annual growth rates confirms the trend occurring at the national level, with investors taking over the running from owner-occupiers and, by extension, first home buyers.  


As can be seen from this next chart, owner-occupier commitments are still at very high levels in all states. However, in recent months, the pace of increase has slowed in New South Wales and Victoria, while commitments have stopped rising in Queensland, Western Australia and South Australia. 


Investor commitments are now accelerating, reflecting this segment's more delayed pick-up in this cycle, which appears to have needed an improvement in market fundamentals and for some of the incentives to owner-occupiers to have reduced.  


Housing Finance — May | Insights

Today's report remained consistent with a very strong housing market, though it appears that as this cycle has progressed, investors are having an increasing influence with commitments in May reaching their highest level in nearly 6 years. Activity from owner-occupiers is still very strong, in particular from upgraders, but first home buyer activity is likely past its peak for this cycle with the HomeBuilder scheme having expired to new applicants and after the sharp rise in house prices over the past 12 months.  

Wednesday, June 30, 2021

Australia's trade surplus widens to $9.7bn in May

Australia's trade surplus for May came in below expectations at $9.68bn, though this was still the nation's third-highest monthly surplus on record. Growth in export earnings lifted as both iron ore and total rural exports hit record highs. Imports have continued to advance, reflecting the robust momentum in the economic recovery. 

International Trade — May | By the numbers
  • Australia's monthly trade surplus increased by $1.52bn to $9.68bn in May, though this was short of the median estimate for $10.5bn. April's surplus was revised up to $8.16bn from $8.03bn reported initially. 
  • Export earnings advanced by 6.1%m/m to $42.23bn (prior +3.3%m/m). With sizeable declines from the initial stages of the pandemic remaining in the 12-month calculation, annual growth accelerated to 23.1% from 8.2%.  
  • Import spending lifted 2.9% for the month to $32.55bn, reversing the 2.7% fall in the month prior. As with exports, base effects sent annual growth higher to 17.7% from 8.0%. 


International Trade — May | The details

Growth in export earnings increased pace in May rising by 6.6% following a 3.3% uplift in April. This brought export credits in May to $42.23bn, its highest level since September 2019. Earnings from both goods (6.3%) and services (4.7%) exports advanced in the month. The increase in the former was driven by a 6.6% rise from non-rural goods, reflecting metal ores and minerals (mainly iron ore) exports rising to record highs at $18bn, equating to 42.6% of total exports in May. Detailed data from the ABS indicated that the increase was supported by both higher iron ore prices and a rebound in volumes after falling in April. 


The rural sector has been a major success story for the Australian economy in its recovery from the pandemic shock following drought-breaking rain early last year. Exports from the sector hit a record high in May ($4.5bn) to be up 31% on a year earlier and 53% above the recent trough in July last year. This has been driven by a surge in cereal grain production, with exports up 168% over the year. Exports of wool (102%yr) and other rural goods (17%) have also rebounded strongly. 


Non-monetary gold exports lifted by a modest 2.3% for the category in May to $1.82bn. Services exports remain significantly lower than prior to the pandemic due to the border closure, though they lifted by 4.7% in May. 


Turning to imports, total expenditure increased by 2.9% to $32.55bn in May, broadly in line with pre-pandemic levels. Imports have rebounded by 17.7% from the depths of the lockdowns last year, reflecting the reopening-driven boost to domestic demand conditions. All categories have contributed to this upswing. Consumption goods lifted by 1% in May to be 28% higher over the year and around 18% above pre-pandemic levels. Notably, imports of passenger vehicles have soared over the past year (139%). 


Capital goods advanced another 3.2% for the month, taking annual growth to 17.2%. The rebound in economic conditions, strong business sentiment, tax incentives and accommodative financing conditions have boosted spending on equipment and industrial machinery (22.6%yr). Intermediate goods posted a modest 0.5% rise in the month but are sharply higher over the year (17.7%). This broadly reflects the very strong conditions in surveys of manufacturing activity both in Australia and globally, which was a shift driven by the pandemic through spending patterns rotating away from services into goods. Lastly, services imports were up 4.6% for the month and 15.5% for the year, but this is from a very low base due to spending being crunched by the travel restrictions.   


International Trade — May | Insights

The trade surplus for May widened out to $9.68bn, making this the third-highest monthly surplus on record. Export earnings have accelerated on the back of elevated iron ore prices, currently trading above US$200/t on global exchanges despite the US dollar proving stronger than many had anticipated in 2021. This, together with the rebound in the rural sector, is boosting national income. Spending on imports continues to rebound in line with the robust recovery in the domestic economy and has recovered to pre-pandemic levels.    

Friday, June 25, 2021

Macro (Re)view (25/6) | Views from all sides

Market themes continue to develop around prospects for policy normalisation in the US following the hawkish interpretation taken away from last week's Federal Reserve meeting. A host of public appearances by FOMC members this week provided a range of differing perspectives on the matter. On the dovish side is Committee Chair Jerome Powell who in a Testimony appearance this week reiterated to lawmakers that high inflation readings would likely prove transitory, easing as the supply-side constraints evident in the reopening process abate. Also leaning dovish is New York Fed President John Williams who expects high inflation to roll over towards the Committee's 2% target next year and hold around that pace in 2023. More hawkish comments in calling for rate hikes in 2022 on the basis that high inflation could persist came from the likes of St. Louis Fed President James Bullard, the Atlanta Fed's Raphael Bostic and President of the Dallas Fed Robert Kaplan. On asset purchases, both Bostic and Kaplan thought that the progress in the recovery meant that the timeline for tapering could be brought forward. Meanwhile, several other Committee members, including current voters Bowman, Daly and Barkin, also spoke publically this week but did not put forward predictions around the timing for liftoff. The Fed's preferred measure of inflation continued to lift rising to 3.4%Y/Y in May from 3.1%, matching the median estimate. Meanwhile, personal income (-2.0%m/m) and spending (0.0%m/m) continued to unwind after the stimulus payments earlier in the year. For the second consecutive month, services spending (0.7%m/m) outperformed goods spending (-1.3%), but a return back towards their pre-pandemic shares of spending still remains a long way off.   

Switching to Europe where, as covered last week, officials from the European Central Bank continued to press the need for policy to remain very accommodative to guard against the risk of financing conditions tightening and potentially weighing on the recovery. ECB President Christine Lagarde told the European Parliament this week that the economy was expected to rebound sharply over the second half of the year and that while inflation would likely rise further, it was mainly the result of temporary factors from reopenings and supply-side constraints. Strong preliminary PMI readings for June reflected the optimism around the near-term outlook in the euro area, with activity on the composite index (59.2) rising at its fastest pace in 15 years, driven by a rebounding services sector with restrictions easing. Households also sense the optimism as the EU's consumer confidence indicator lifted further in June to sit close to record highs. In the UK, the Bank of England left all policy settings unchanged, maintaining rates at 0.1% and asset purchases at £895 at this week's meeting. The Monetary Policy Committee gave a relatively upbeat assessment of conditions in noting that the UK economy was on track to return to pre-pandemic levels of output before the turn of the year and that as the rebound occurred, a period of excess demand was expected leading to inflation temporarily spiking above the 2% target. The strong outlook will continue to see markets speculating on when rate hikes might come across the MPC's radar, though any hint of this was avoided in this week's statement.      

— — 

Turning to developments in Australia where the pandemic is starting to cause problems again through increased caseloads in New South Wales leading to a localised lockdown in Sydney and the reintroduction of internal border controls. But at the same time, Victoria continues to reopen from its recent lockdown and capacity restrictions in Queensland are being rolled back further. High-frequency data on consumer confidence will likely fall sharply on the back of these COVID concerns when it is reported next Tuesday given that it will be coming off a 1.3% rise for the week through to 19-20 June that was largely attributed to May's strong labour market update (see here), while the readings in Sydney (5.2%wk/wk) and for the rest of the state (2.8%wk/wk) had shown more elevated gains over the period. May's advanced estimate of retail sales showed the impact of the early stages of Victoria's lockdown as spending in the state fell by 1.5%m/m around a familiar stay-at-home composition with basic food up sharply (4.0%m/m) as discretionary categories all declined. But despite the fall in Victoria, offsetting gains of 1.5% came through in Queensland and Western Australia, which resulted in national turnover increasing very slightly (0.1%) on the month prior. This left monthly retail sales 7.4% higher than a year earlier, with the level at $31.1bn remaining sharply above their pre-pandemic trajectory. 

Also highlighting the impact of the disruption to activity from the Victorian lockdown was the 0.9% fall in the ABS's national payroll jobs index for the fortnight to 5 June. Unsurprisingly, payroll jobs showed the sharpest decline in Victoria (-2.1%), though the readings across the other states had also been soft. However, there remained positive signs for the strength in labour market conditions continuing as internet-advertised job vacancies reported by the government lifted by a further 1.9% in May to be at their highest level (as a per cent of the labour force) since 2011 at around 1.8%. While the strong rebound in the economy helps to explain the acceleration in labour demand, there are also other factors that are contributing to elevated vacancies. Insights into this were provided in the ABS's latest business survey for June in which 27% of firms reported encountering difficulties finding suitable labour for their requirements. For firms in this situation, the top 3 reasons cited behind the difficulties included a lack of applicants (74%), skills or qualifications mismatches (66%), and the impact of the border closures (32%). Of late, there has been speculation of an acceleration in wages growth given the strength in the labour market. But that seems more likely to be more of a micro than a macro story. Higher wages might go some way to encouraging more applicants to industries that need labour, but it seems unlikely to be the response from firms if they perceive that the required skills either aren't available in the first instance or, secondary to that, if suitable labour can't be easily accessed. Consider also that while broad measures of conditions in the labour market continue to strengthen, employment in many industries is still recovering from the COVID crisis and is yet to return to pre-pandemic levels more than a year on from the national lockdown (see chart below). With the recovery still having some way to go, a broad-based uplift in wages appears an unlikely scenario. 
        
Chart of the week 

As noted by the RBA's Assistant Governor Luci Ellis in a speech this week, accommodative monetary policy settings will remain appropriate for as long as spare capacity in the economy persists. Somewhat pushing back against the notion of pre-emptive tightening was the interesting observation that with the pandemic leading to many structural adjustments in the economy, this process can be made smoother if policy settings continue to support robust demand conditions. Ellis outlined that if the economic recovery can be sustained into a durable expansion, workers will be able to more easily shift between industries and businesses will be able to more readily adapt their operating models.